Global squeeze:
- China commercial diesel inventories fell to 11.1 mt end Oct — lowest since records began 2011.
- China diesel exports expected below 0.8 million tonnes Nov 2026, vs 1.33 mt Aug and 1.8 mt Sep — sharp cut due to domestic demand + export curbs.
- US and other markets inventories also declining — IEA Nov Oil Market Report: severe tightness in product supply, especially diesel, remains overriding concern.
- Global diesel/gasoil availability fell 1.7 mb/d Q3 vs year earlier per IEA + Energy Institute, after 1.5 mb/d fall Q2 — due to US-Iran war disrupting Middle East, Ukrainian drone attacks on Russian refineries, Houthi Red Sea shipping attacks, Strait of Hormuz closure fears, export restrictions China + Russia.
- Wholesale diesel prices surpassed $200/bbl Sep, $220 Europe US, near double pre-war.
IEA members Oct 15 agreed accelerated emergency stock releases including over 20 million barrels diesel — bridge until refinery system recovers.
Why India benefits:
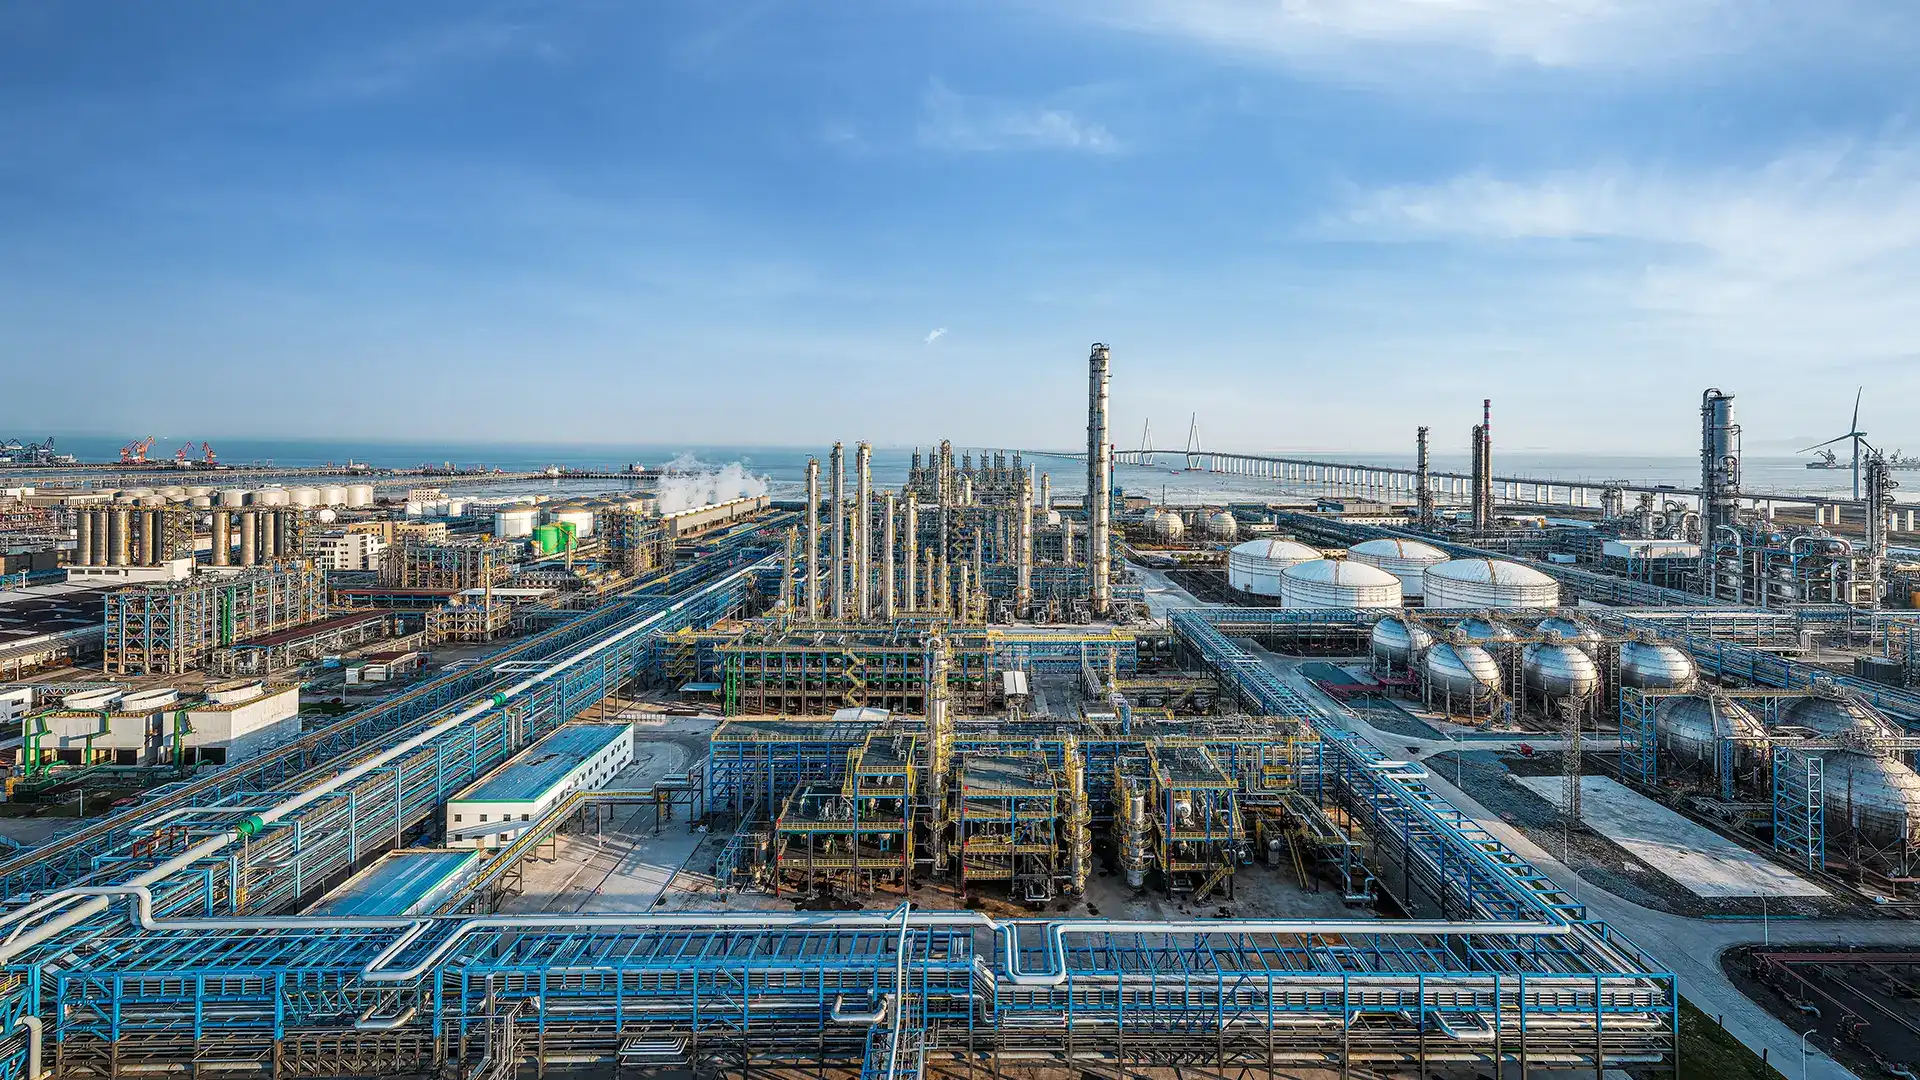
India has world's fourth-largest refining capacity after China, US, Russia. Producing more than it consumes — Apr-Sep produced 59 mt vs consumption 46 mt per PPAC.
Equirus: reduction in Chinese exports alongside lower inventories intensifies competition for available diesel — supports refining cracks.
- Gasoil crack (difference crude vs diesel — indicator of refiner earning) rose 0.9% WoW to $61.4 per barrel week ended Nov 13 — down 14.4% over 3 months but still elevated.
- Strong diesel cracks already supporting profitability — favours standalone refiners like Reliance Industries RIL — greater flexibility to divert to exports vs OMCs Indian Oil, BPCL, HPCL which cater domestic.
Indian diesel exports: Kpler — Sep 596k bpd vs avg 482k bpd in 2026 so far. Oct jumped to 2.90 mt — highest in 12 months, 700k b/d vs 620k Sep, highest since Sep 2025. Refinery runs above 100% utilization, limited maintenance.
ICRA VP Prashant Vasisht: Diesel export big advantage as cracks very high. Realisation somewhat dented by export duty but export-oriented refineries exempt. High utilisation + access to competitively priced crude including Russian barrels supports economics.
Long-planned expansions adding opportunity: State-owned refiners plan add 16.5 mt annual diesel capacity next year — IOC +8 mt, HPCL Rajasthan refinery 3 mt, Numaligarh Assam +3 mt, BPCL +1.5 mt — overall capacity from 267 mt to 300 mt by 2030. Originally for domestic growth, now global export window.
Govt levies: Special Additional Excise Duty SAED — effective Oct 16, petrol duty raised Rs 0.50 to 2.50/litre, diesel reduced from Rs 16 to 8.50/litre to balance domestic vs export.
Equirus expects sustained tightness to remain favourable even if crude eases — to cushion net oil and gas bill which rose 35% YoY to $81.1 bn H1 FY27 per PPAC, but unlikely to fully offset import cost.
#Diesel #Refiners #Reliance #IEA #Equirus #China #GlobalCrunch #Exports #RefiningMargins #Oil