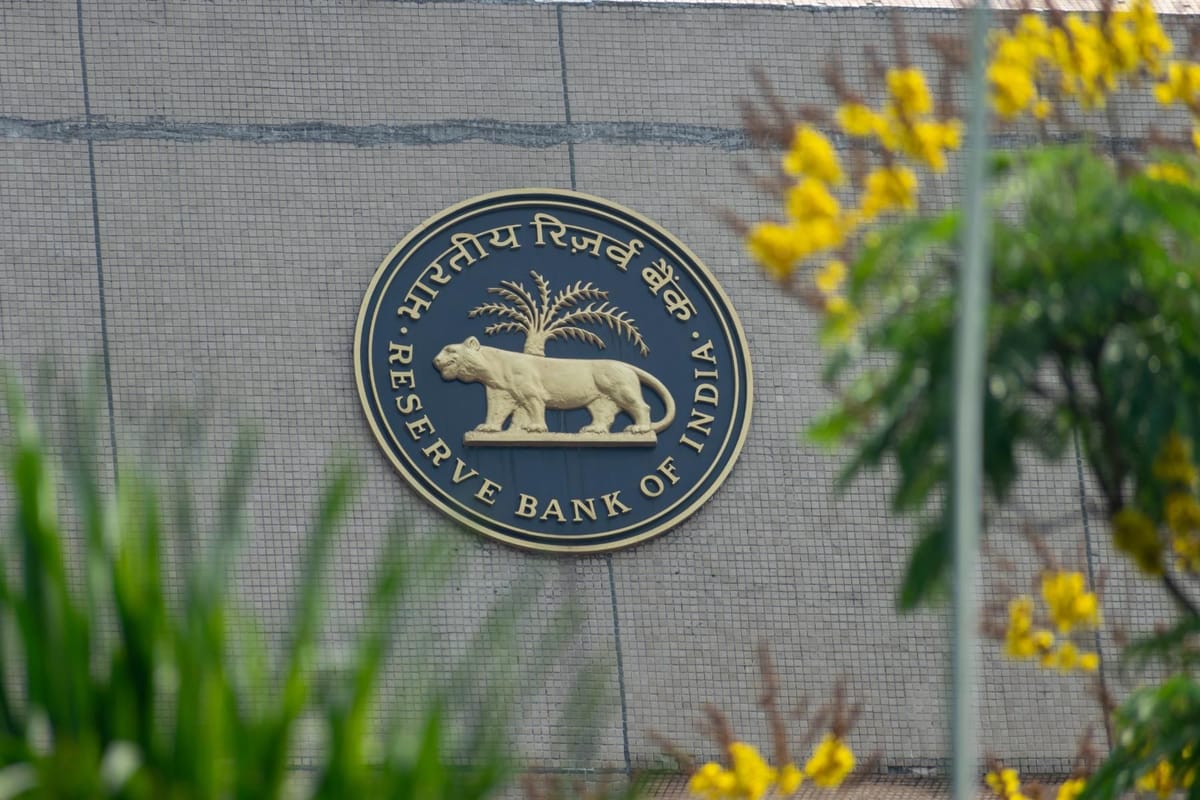
RBI Governor Sanjay Malhotra's decision on October 8 was not just a rate hike; it was a tone shift. From neutral to calibrated tightening. Translation: cuts are off the table, hikes or long pauses are in.
Why now? Two triggers: West Asia conflict escalated in September, crude became volatile, and global inflation is hardening. Domestically, headline inflation at 5.8% may breach the 4±2% band in Q3.
For Indian households, this is heavy lifting. The policy repo at 5.5% means SDF at 5.25% and MSF at 5.75%. EMIs will not fall. For small businesses, working capital gets costlier.
Yet the context is Indian resilience. Growth forecast at 6.5% in FY27, GST collections steady, forex reserves stable. The MPC is choosing price stability over growth cheerleading - classic RBI conservatism.
Read more - Hawk Time At Mint Street
The deeper question: With India-US trade talks at a plateau and tariffs threatening export surplus, can India afford tighter money? Malhotra is betting that killing inflation expectations now prevents a harder landing later. For a consumption economy, it's a bitter but necessary pill.
Read more - Swiss Fix For TEPA
Tags: RBI, Repo Rate, Monetary Policy, Sanjay Malhotra, Inflation, Calibrated Tightening, Indian Economy, Interest Rates, MPC, Crude Oil Impact